How Professional Dent Repair Restores Your Car’s Appearance

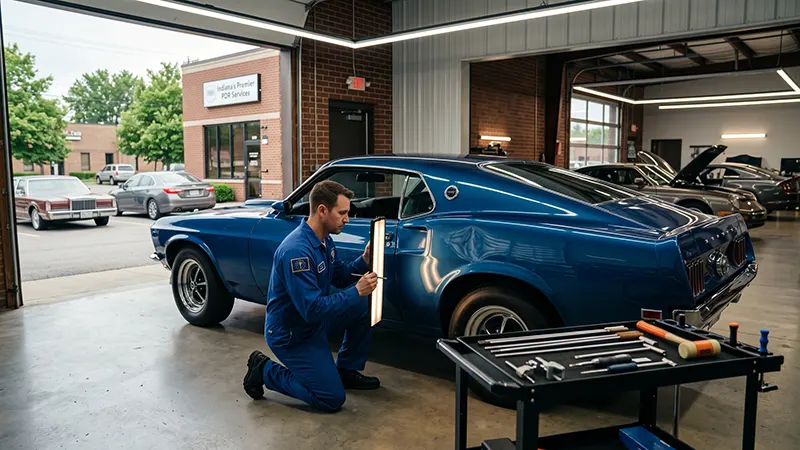
Dents and blemishes can give your car a bad appearance. Doors, fenders, hoods, and quarter panels can all be marred by minor collisions or careless door swings. A dent might appear to be a minor issue. But if it is fixed incorrectly, it could greatly affect the overall appearance of your vehicle.

Choosing the best Auto Dent Removal Service Indiana can help a lot in restoring damaged panels. The right service will do so without making a minor repair seem like a major one.

Why Dents Change Your Car’s Appearance

A dent cannot be limited to causing a shallow mark in metal. It causes a change in the way light reflects off the panel. Not to mention, it can highlight an imperfection as small as a speckle on the glass. A car might also appear to be aging and not well-maintained when its surface area is uneven.

Lines that shape … READ MORE >>>

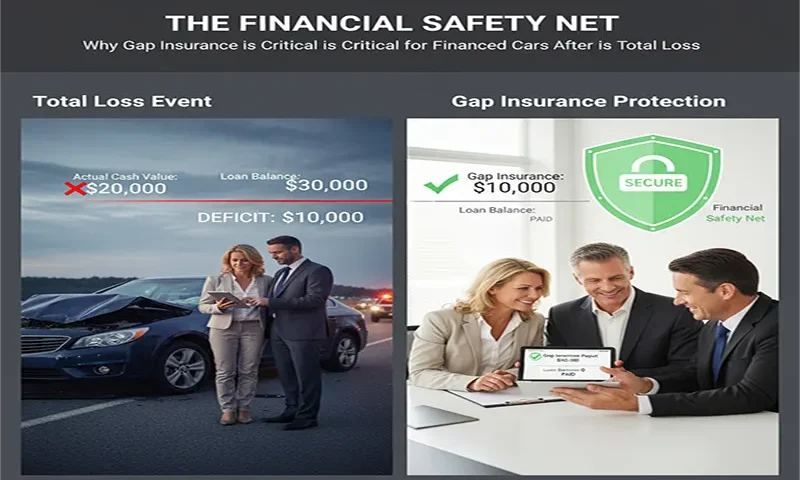
The Financial Safety Net: Why Gap Insurance is Critical for Financed Cars After a Total Loss

When you finance a vehicle, you are entering into a legal agreement to pay back a specific amount of money, regardless of what happens to the car. Many new car owners operate under the assumption that their comprehensive auto insurance will “make them whole” if the vehicle is totaled. Unfortunately, that is often a costly misconception.

If your vehicle is declared a total loss, your primary insurance provider pays only the Actual Cash Value (ACV)—the fair market value of the car at the time of the accident—not what you paid for it or what you currently owe on your loan. Because new cars depreciate rapidly, there is often a significant difference between your loan balance and your car’s market value. This is known as the “depreciation gap,” and without Gap Insurance, that gap is a debt you are legally required to pay out of your own pocket.

1.

… READ MORE >>>
The Clean Slate Strategy: How New Drivers Can Secure the Cheapest Car Insurance

Securing car insurance as a new driver often feels like a paradox: you need the insurance to drive, but the cost to get that insurance is often prohibitively high. This is what many call the “New Driver Penalty.” Because insurers lack a history of your driving behavior, they view you through a statistical lens—statistically, new drivers are more likely to be involved in accidents.

However, having a clean driving record is your most valuable financial asset. It is the foundation upon which you will build your insurance history, and when managed correctly, it is the fastest way to shed that “high-risk” label and drop your premiums into the standard, more affordable bracket.

1. The Foundations of Pricing: Why You Are Rated as “High Risk”

Insurers calculate premiums based on risk probability. For a new driver, the lack of a driving record is the primary risk factor.

  • Experience Over Everything: Insurers
… READ MORE >>>
The Tesla Insurance Advantage: A Comprehensive Guide to Protecting Your EV

Owning a Tesla is as much a digital experience as it is a mechanical one. When it comes to insurance, the traditional “set-it-and-forget-it” model is rapidly becoming obsolete. For Tesla owners, insurance is evolving into a real-time, data-driven feedback loop. By understanding how Tesla’s proprietary insurance works compared to legacy providers, you can transform your insurance from a monthly bill into a tool for financial optimization.

1. The Anatomy of Tesla Insurance

Tesla Insurance represents a fundamental shift in the industry. Traditional insurers calculate your premiums based on broad statistical demographic data—your age, credit score, and zip code. Tesla, however, utilizes real-time vehicle data to assign a “Safety Score.”

This score is calculated daily based on your actual driving habits. Factors like hard braking, aggressive turning, forward collision warnings, and unsafe following distances all contribute to your score. If you drive carefully, your “Safety Score” remains high, potentially lowering your … READ MORE >>>

The Data-Driven Driver: How to Master Telematics Apps to Slash Your Auto Insurance Premiums

For decades, your car insurance premium was largely determined by demographic “buckets”: your age, your zip code, and your credit score. If you were a safe driver living in a high-density area, you were essentially subsidizing the risk of other, less-careful drivers in your demographic.

Telematics—often referred to as usage-based insurance (UBI)—changes this dynamic. By utilizing a smartphone app or a plug-in device to monitor your real-time driving habits, insurers can shift from “group risk” to “individualized risk.” If you drive safely, you are no longer a statistic; you are an asset. Here is how to master your driving score and leverage telematics to lower your premiums.

1. The Anatomy of a Driving Score

When you install a telematics app, it begins collecting data points the moment you start your engine. Understanding what the algorithm is looking for is the first step toward optimization.

  • The “Big Five”: Most apps monitor
… READ MORE >>>